Local Pickup Benefit
Enjoy up to $100 off when you pick up your order at our studio.


Somewhere in most offices there is a drawer. A branded notebook. Two water bottles. A pen with somebody's logo on it that writes badly enough that nobody has used it or thrown it away.
That drawer is where most corporate gifting ends: an object nobody chose, sent to a list nobody curated. The people sending it usually know this. They send it anyway, because the alternative takes more thought and the budget arrives late.
There is a reason the branded version persists, and it is not sentiment. It is a tax rule from a different era that quietly shapes the whole category.
Business gifts are deductible only up to $25 per recipient per year, which means above about $25 the tax treatment stops mattering and the only question is whether the recipient keeps the thing. The exception is items costing $4 or less carrying your permanently imprinted name — those count as advertising, not gifts. That single threshold explains the entire branded-pen industry.
Business gifts are deductible up to $25 per recipient per tax year. Not per gift — per person, for the whole year. Send someone a $60 gift in March and a $40 one in December and you have deducted $25.
A few details worth knowing:
Here is the mechanic that shapes the category.
An item costing $4 or less, carrying your business name permanently and clearly imprinted, distributed widely, is not a gift at all in the eyes of the rules. It is advertising — fully deductible, no cap.
That is the whole economic logic of branded pens, and it collapses at $4.01. Above that threshold, putting your logo on something earns you no additional deduction whatsoever. It just puts your logo on someone's desk, where they have to either display your marketing or give it away.
So the honest framing is this: either spend under $4 and accept you are buying advertising, or spend properly and stop pretending the tax treatment is a factor. There is no middle ground where a $60 branded item is clever.
There is one structural workaround, and it is legitimate rather than clever.
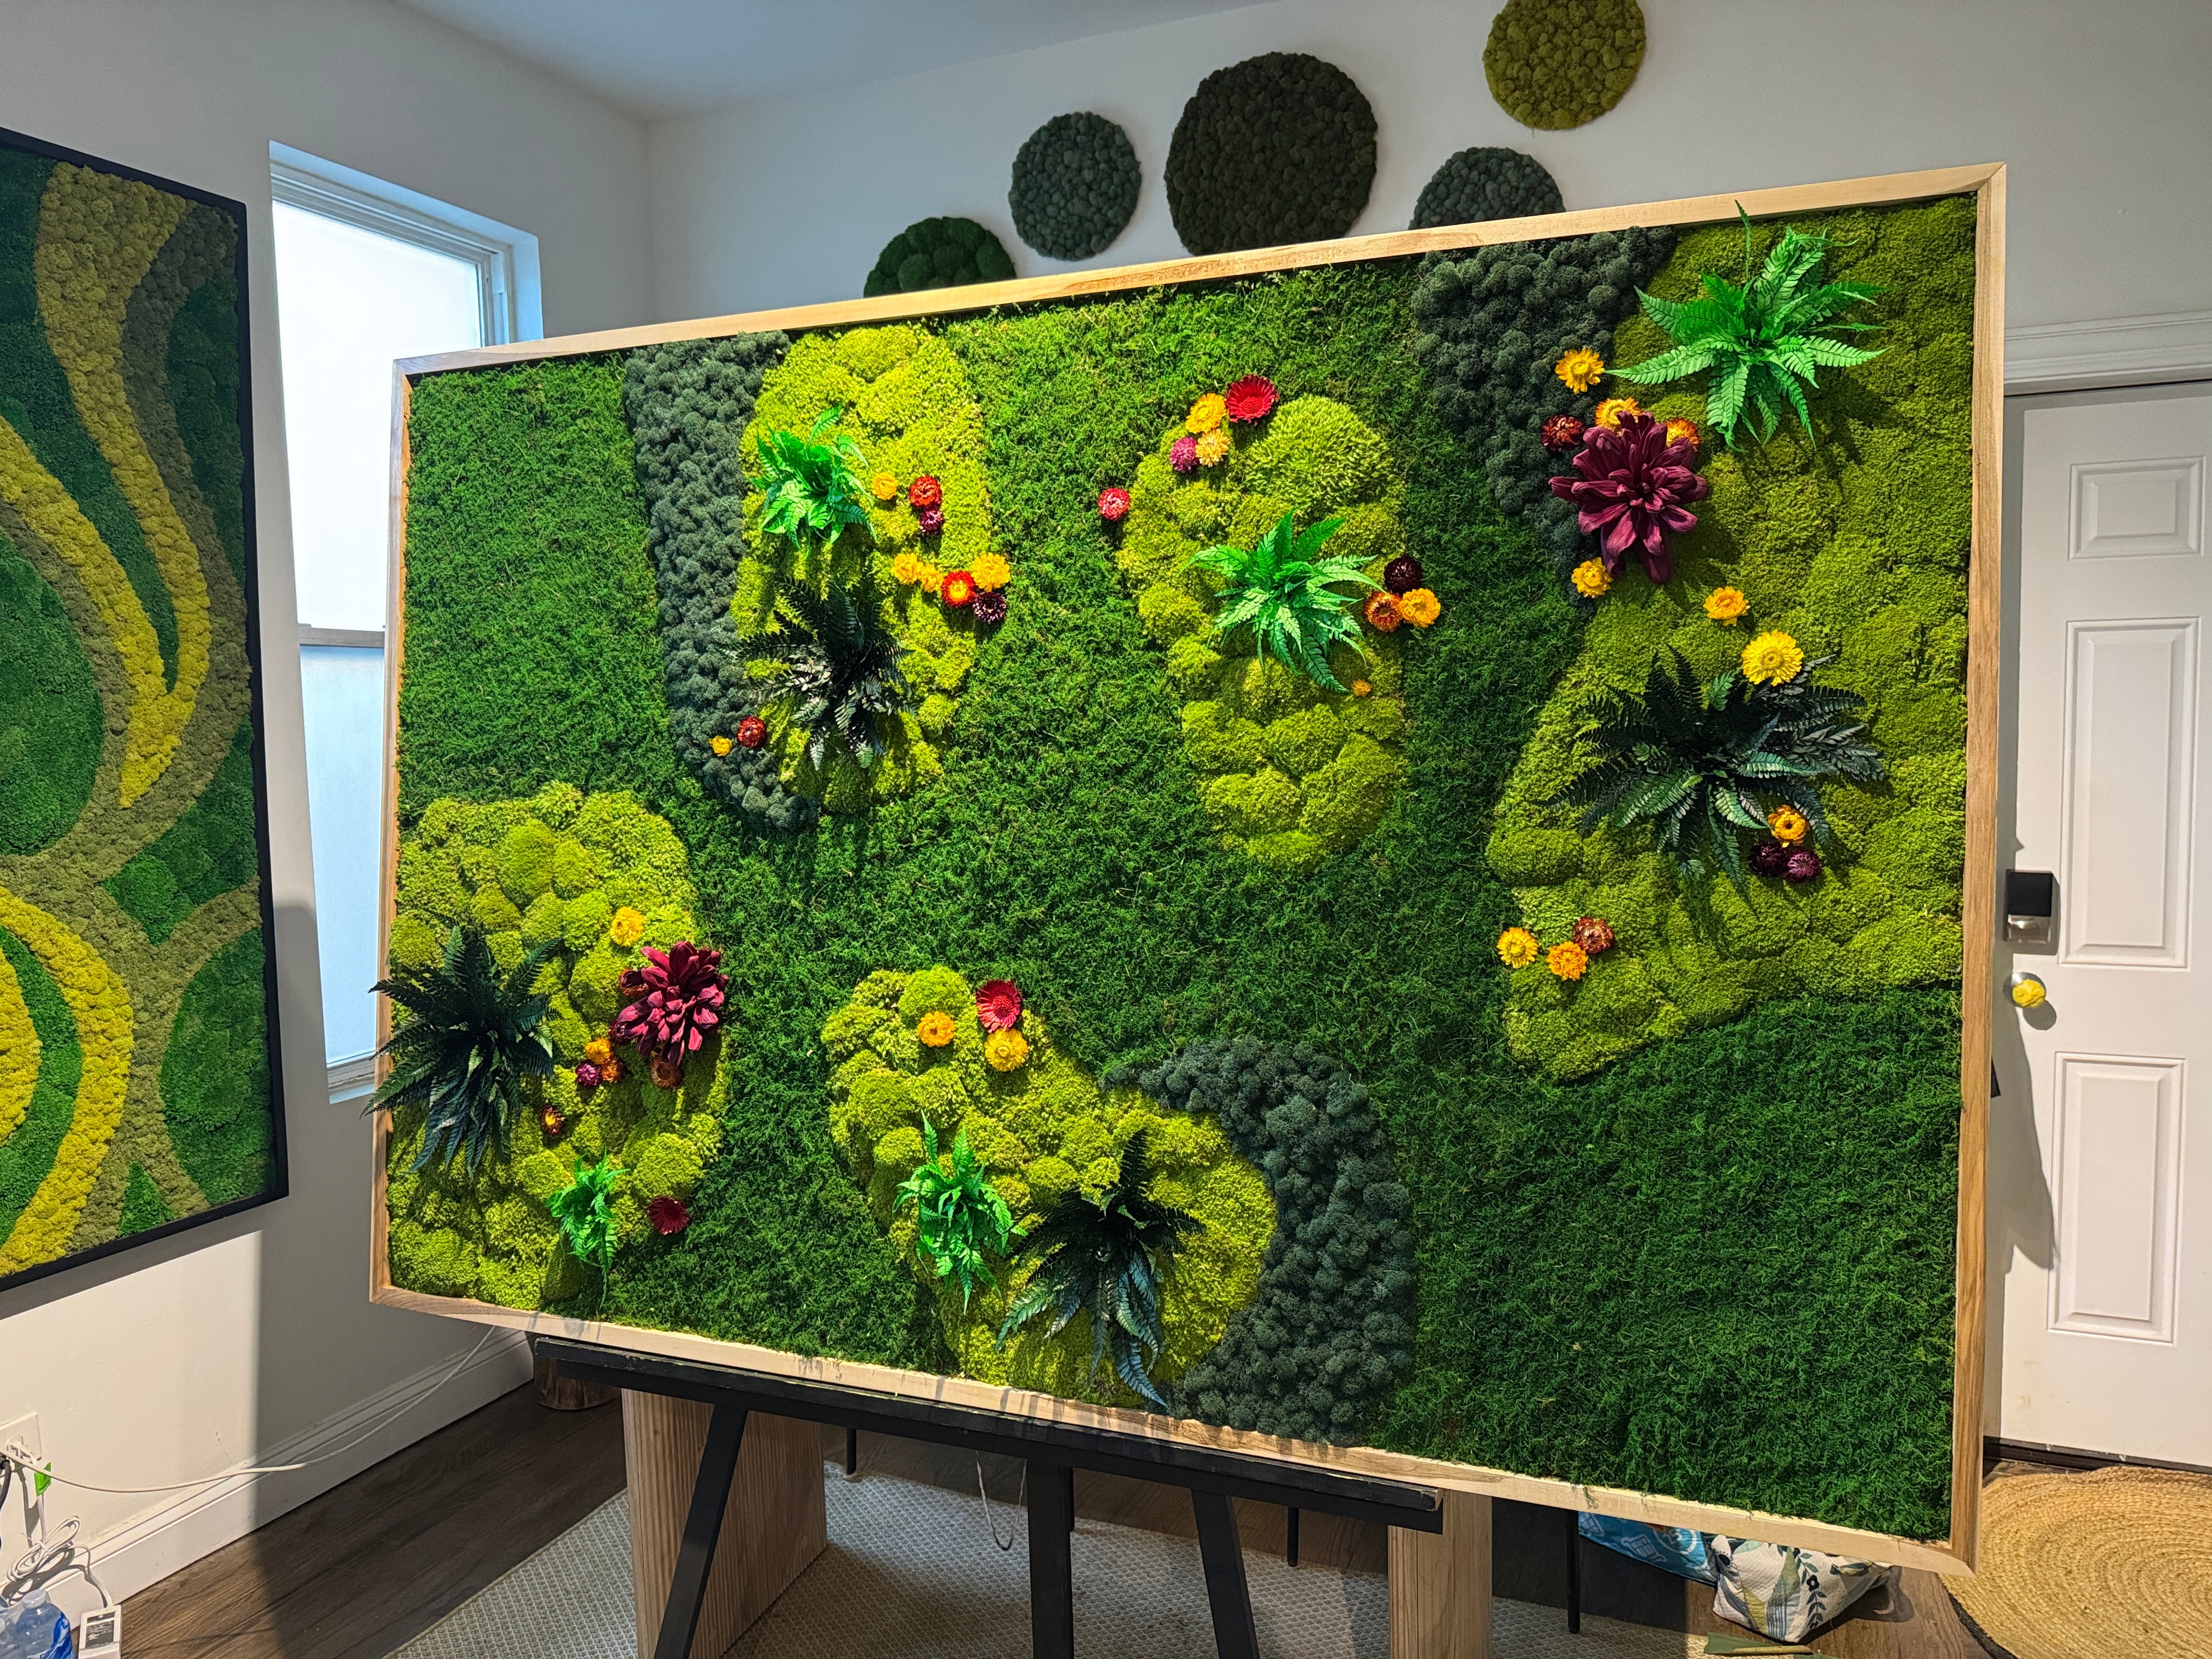
A gift to a company or entity for general use — something intended for the office rather than for one named individual — is not subject to the $25 per-person cap. A piece for a firm's conference room or reception area is a different category from a piece for the managing partner's study.
That is also usually the better gift. An object with a place in a shared space gets seen by everyone in the practice, including the people who did not sign the contract but who will recommend you next time.
Worth checking before you send anything, because the limits are specific and the penalties are not yours to absorb.
| Recipient | Limit |
|---|---|
| Broker-dealers (FINRA Rule 3220) | $300 per person per year, raised from $100 in March 2026 |
| Municipal securities (MSRB G-20) | $300, following FINRA |
| Federal executive-branch employees | $20 per occasion, $50 per source per year |
The federal rule has a trap in it: the recipient cannot pay the difference to accept something over $20. Their only option is to decline it. A generous gift to a government client creates an awkward conversation rather than goodwill.
Financial-services firms must also aggregate everything given to one person across the whole firm over twelve months, so your gift may collide with a colleague's.
There is a consistent gap in the industry data between what recipients expect — around $100 — and what companies actually spend, with a median closer to $30. Acceptance rates rise with value, and roughly half of senders give the identical item to every client.
Treat those figures as directional; most of them come from gifting platforms with an interest in the answer. But the direction is not in doubt, and it matches what anyone who has received corporate gifts already knows.
A more useful way to think about the budget: once the deduction is capped at $25 regardless, the spend is not really a gift line. It is a media line. The question becomes how many years the object stays visible in a client's office, and how many people see it there.
If your clients are the people who specify work for other clients, the calculation shifts again. A gift that sits in a design practice's studio is seen by everyone who visits, including their clients.
We work with this audience regularly — our business and trade side is largely designers, architects and firms commissioning for their own spaces as well as their clients'.
The constraint on a good corporate gift is almost never budget. It is the calendar.
Handmade work does not compress. Our own frames run four to five weeks and bowls two to three, with custom and commercial projects taking thirty to sixty days. A run of twenty is not twenty times one piece, but it is not one piece either. The practical deadline for December delivery is a budget locked by late summer, and most companies approve their gifting spend in October.
There is a materials point specific to what we make. Preserved moss arrives in lots that do not color-match perfectly across a large run. Twenty identical pieces is a genuinely different order from twenty in a family — the first needs a single lot reserved in advance, the second does not. Worth raising early rather than discovering in November.
Up to $25 per recipient per tax year. That is a limit per person for the whole year, not per gift, and it has not moved in a long time.
Only below $4 per item, where a permanently imprinted name makes it advertising rather than a gift. Above $4, a logo earns no additional deduction.
Check their limit first. Broker-dealers are capped at $300 per person per year, and federal employees at $20 per occasion — and a federal employee cannot pay the difference on anything over that, only decline it.
Recipients expect roughly $100; median spend is closer to $30. Since the deduction caps at $25 either way, the practical question is how long the object stays in their office rather than what it cost.
Not for employees. Cash and general-purpose gift cards are always taxable wages regardless of amount, with no small-value exception.
For December delivery, lock the budget by late summer. Our frames run four to five weeks and bowls two to three, custom and commercial work thirty to sixty days, and matched sets need a single materials lot reserved up front.
Every piece we make is built by hand in our Chicago studio, and we make the frames ourselves — which means a corporate run can be sized, finished and matched to a brief rather than picked from a catalog. Talk to us through our business page, see the commercial portfolio, or request a free estimate with your quantity and date. For something branded to the recipient's own office, logo walls are the other direction.
The Moss Shop specializes in handcrafted preserved moss artwork for homes and businesses.